

Roof Inspection for Mortgage Approval: What to Do First
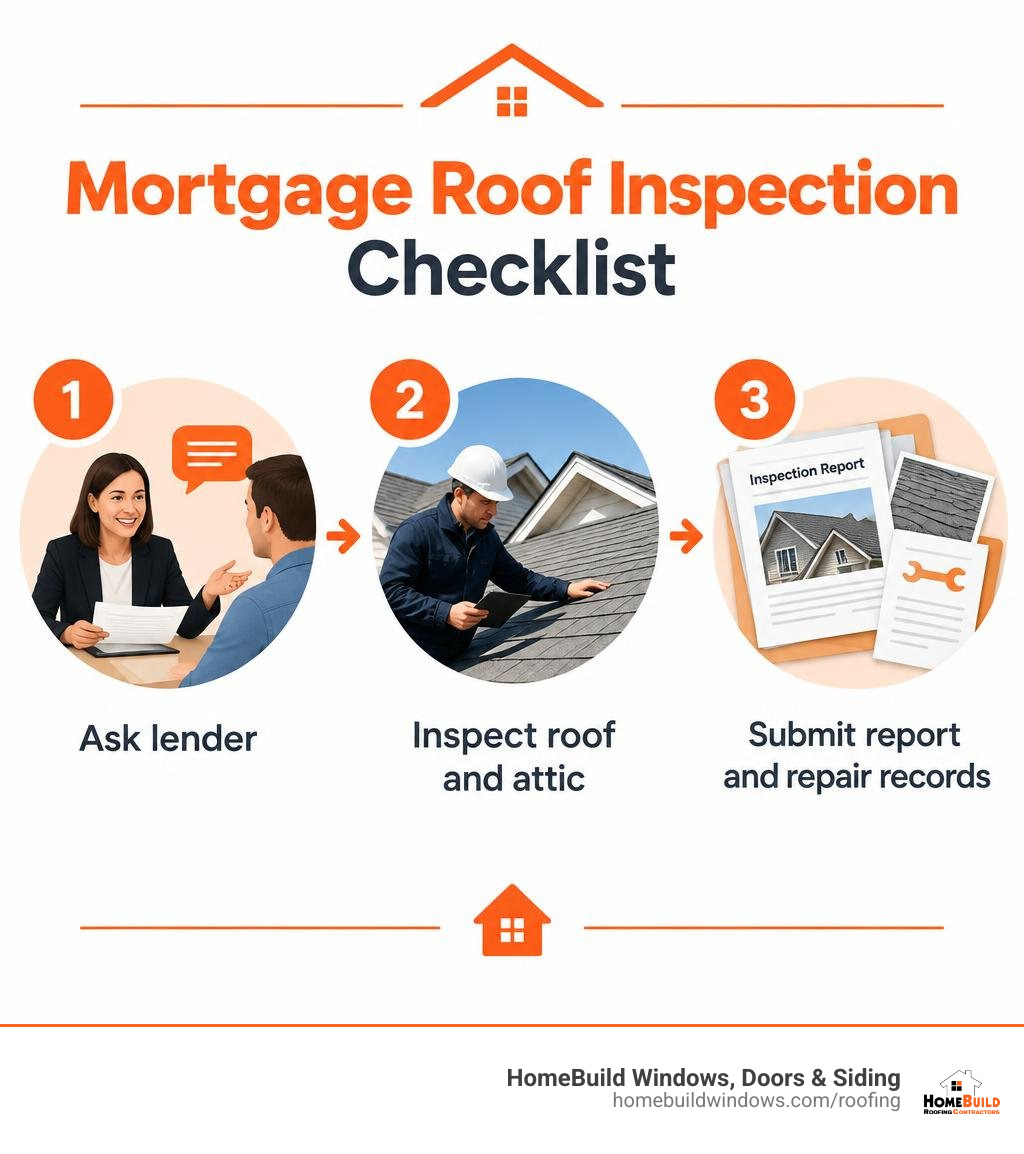
If a lender flags the roof, ask exactly what evidence it needs before booking an inspection. Arrange a professional roof and attic inspection, then send the lender the written report, photos, and any repair records. A mortgage appraisal may spot visible problems, but it is not a full roof inspection.
Leaks, missing shingles, and a sagging roof can delay a sale. If you are selling a Chicago-area home, check these issues before listing.
I’m Steve Mlynek, HomeBuild’s founder, with over 20 years of home exterior experience. Our licensed and insured roofing team offers owner-supervised work and can help you prepare for a roof inspection for mortgage approval.
Why Lenders Require a Roof Inspection for Mortgage Approval
A mortgage lender invests hundreds of thousands of dollars into a residential property. The physical home serves as the direct collateral securing that loan. If the roof fails, water destroys drywall, insulation, electrical systems, and structural framing.
Lenders demand proof that a roof protects the asset throughout the loan term. According to the MBA Property Inspection Reference Guide, standardized property inspections serve as early warning systems. They protect lenders from deferred maintenance and severe property loss.
An insurer will also refuse to write a homeowners policy on a damaged roof. Without active hazard insurance, an underwriter cannot legally fund the mortgage.
Mortgage Valuation vs. Specialist Roof Inspection for Mortgage Underwriting
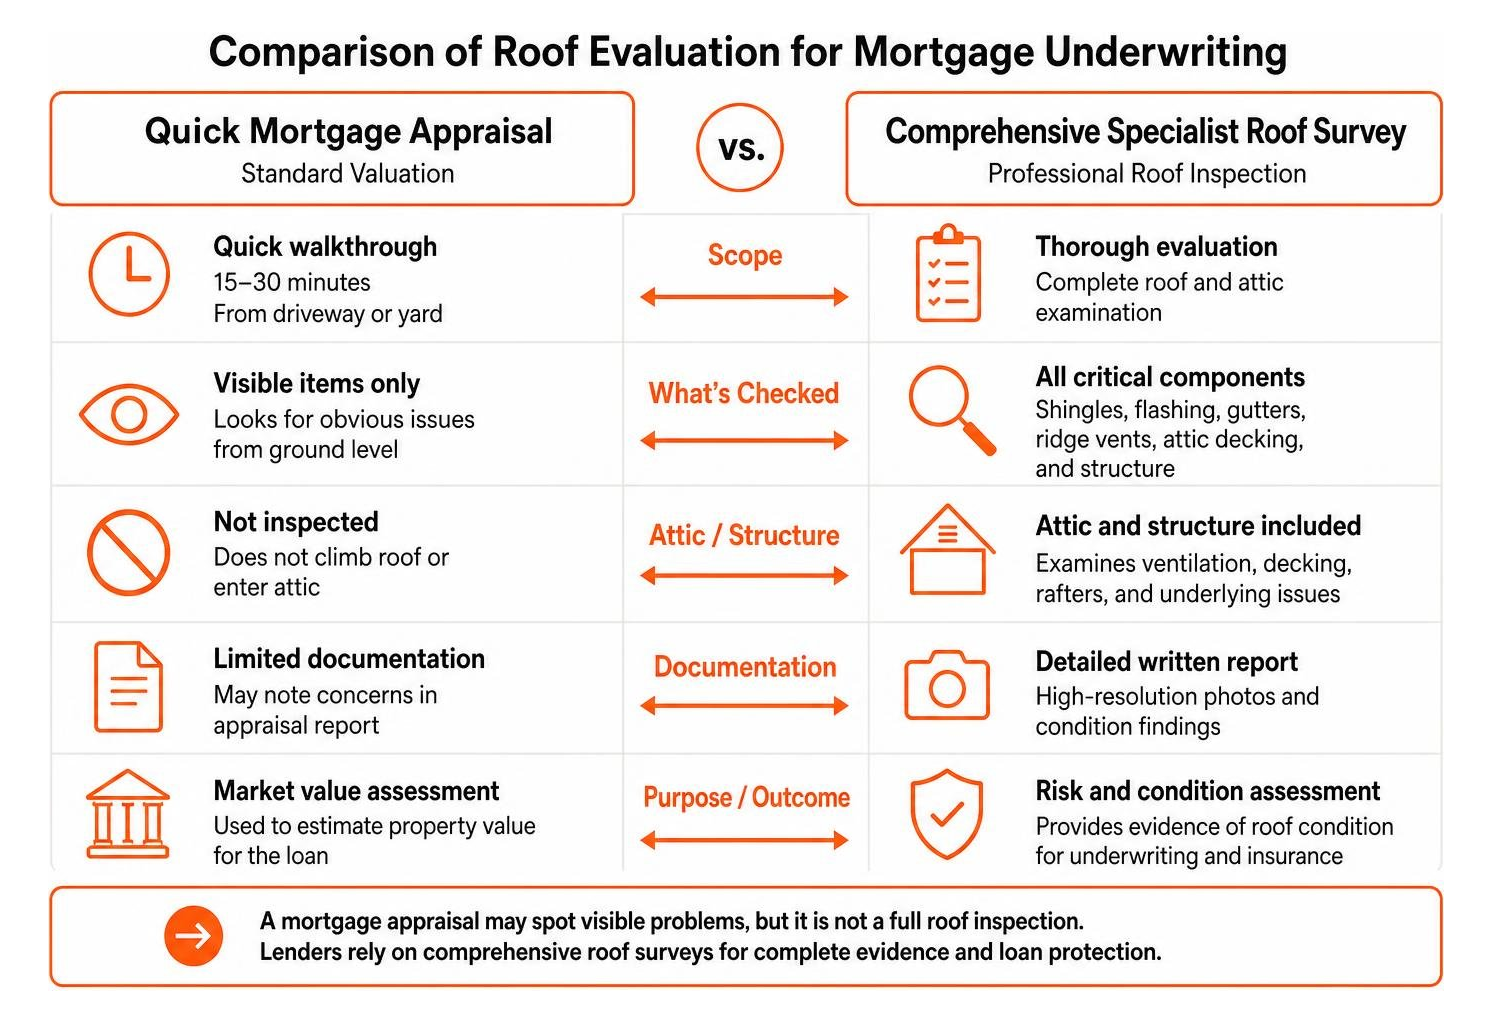
A standard mortgage valuation is not an exhaustive structural assessment. The appraiser conducts a quick 15-to-30-minute walkthrough focused on market value. They look at the roof from the driveway or yard.
Appraisers do not climb onto the roof covering or evaluate attic decking. Hidden moisture, rotted rafters, and minor flashing gaps often go unnoticed during this visit.
In contrast, our professional roof inspections provide complete documentation. We examine shingles, flashings, gutters, ridge vents, and the underlying timber decking. This thorough evidence gives underwriting teams the precise data they require.
Key Property Risks: Collateral Protection, Ice Dams, and Chicagoland Weather
Homes in Cook County, DuPage County, and Lake County face severe environmental wear. Chicagoland experiences brutal freeze-thaw cycles, heavy snow loads, and high summer humidity.
In winter, poor attic ventilation causes snow to melt and refreeze at cold eaves. This creates damaging ice dams that force water upward underneath the shingles.
Following a detailed pre-winter roof checklist helps identify ventilation issues before cold weather sets in. Lenders worry because repeated freeze cycles rot roof decking fast.
Common Defects That Stall Mortgage Underwriting and Loan Funding
Underwriters flag specific roof defects that threaten property integrity. When an appraiser spots visible damage, they condition the loan on repairs.
Federal standards outlined in the HUD NSPIRE Roof Assembly Standards mandate swift remediation. Many exterior deficiencies require verified correction within 30 days to satisfy safety rules.
Structural Deterioration, Missing Shingles, and Active Leaks
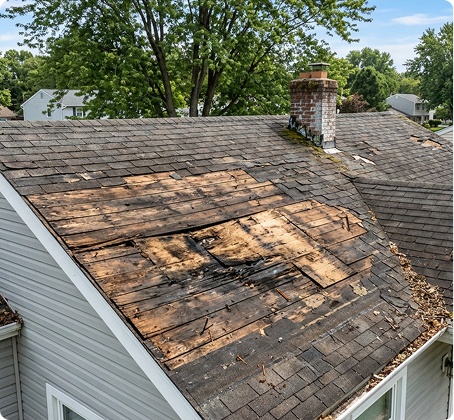
Sagging ridgelines point directly to broken rafters or rotted plywood sheathing. Missing or cracked asphalt shingles expose underlayment to intense wind and rain.
Knowing how to spot roof leak warning signs saves buyers from surprise funding denials. Water stains on ceilings or rotted fascia boards trigger mandatory repairs.
Severe wind and hail storms across the Northwest suburbs frequently bruise shingles. Working with experienced local roof inspectors for hail damage ensures storm impacts are documented accurately for adjusters.
The Spray Foam Insulation Dilemma for Mortgage Lenders
Spray foam insulation creates major underwriting roadblocks during home sales. When contractors apply open-cell or closed-cell foam directly to roof sheathing, they seal the attic.
This barrier conceals roof rafters and decking from visual view. Appraisers cannot verify whether timbers suffer from active leaks, dry rot, or wood-destroying insects.
As detailed by FoamTruth on spray foam and mortgage appraisals, closed-cell foam can trap trapped roof moisture against wood decking. Without original installation permits and moisture scan documentation, lenders may decline the mortgage.
What Appraisers and Lenders Look for in a Certified Roof Report
Mortgage underwriters require structured, third-party proof before removing loan conditions. They reject informal handwritten contractor notes or vague verbal assurances.
Authoritative organizations like the NRCIA mortgage underwriting division establish strict criteria for roof certifications. Standardized reporting reduces lending liability and speeds up loan approvals.
A compliant inspection report must include:
- The inspector’s state license number and original signature.
- High-resolution photographs of every individual roof slope.
- Clear photos of valleys, flashing details, gutters, and chimneys.
- Attic decking observations checking for water penetration and ventilation.
- An objective condition rating and a verified estimate of remaining useful life.
Essential Documentation to Clear Underwriting Flags
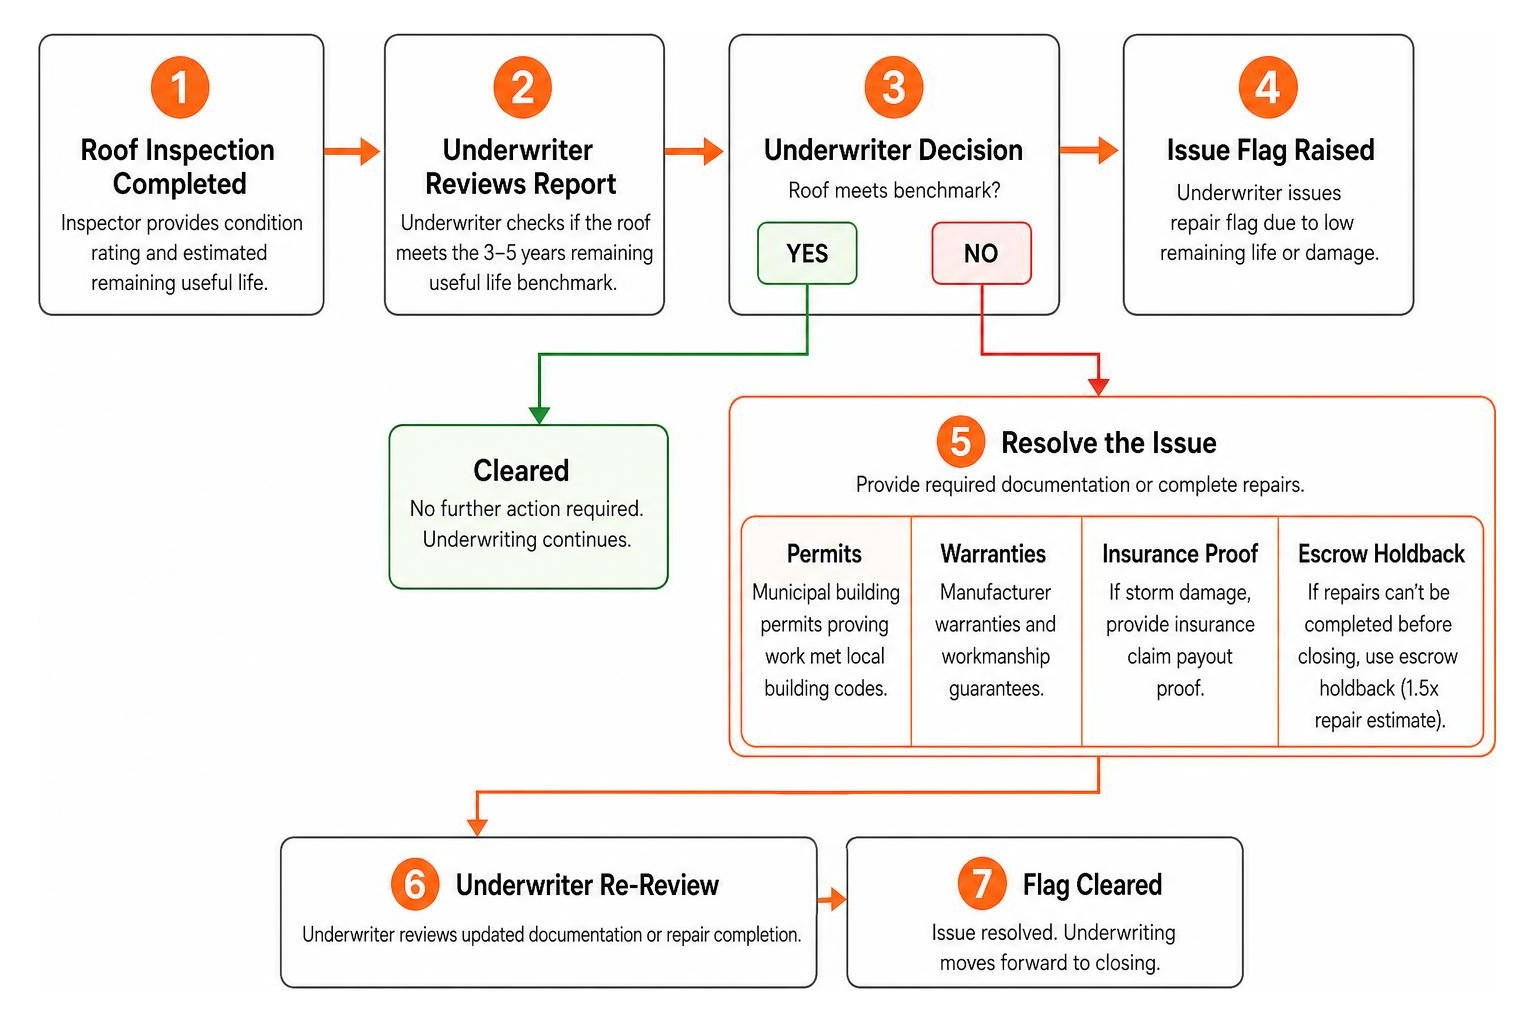
When an underwriter issues a repair flag, gathering proper paperwork resolves the issue. Municipal building permits prove past work met local building codes.
Manufacturer warranties and workmanship guarantees show long-term system durability. If storm damage caused the issue, properly navigating roof insurance claims provides documented payout proofs.
If repairs cannot finish before closing, lenders sometimes allow escrow holdbacks. The closing attorney holds 1.5 times the repair estimate in escrow until work finishes.
Material Lifespan Expectations and Remaining Useful Life
Underwriters generally require a roof to have at least 3 to 5 years of remaining useful life. If a roof is near the end of its life, lenders require replacement before funding.
Understanding the real cost of a new roof helps buyers budget for required replacements accurately.
| Roofing Material | Typical Lifespan | Climate Vulnerability in Chicago | Mortgage Underwriting Risk Level |
|---|---|---|---|
| 3-Tab Asphalt Shingles | 15–20 Years | High wind lift, hail bruising | High (if older than 15 years) |
| Architectural Shingles | 25–30 Years | Strong resistance to wind and snow | Low to Moderate |
| Concrete / Clay Tiles | 50–100 Years | Heavy freeze-thaw cracking | Low (requires strong framing) |
| Natural Slate | 75–100+ Years | Heavy weight, brittle impact | Very Low (decking must be sound) |
| Modified Bitumen / EPDM Flat Roof | 12–20 Years | Ponding water, seam separation | Moderate to High |
Strategic Guide: How to Handle a Roof Inspection for Mortgage Clearance as a Buyer or Seller
Managing a property transaction requires proactive planning around roof condition benchmarks. Around 24% of agreed home sales face delays or cancellation due to preventable inspection findings.
If you are preparing a property in Schaumburg or Hoffman Estates, review our guide on passing a roof inspection in Schaumburg. Pre-listing inspections give sellers time to complete affordable repairs before an appraiser walks the property.
Navigating a Roof Inspection for Mortgage Clearance During Price Negotiations
When an inspection reveals serious wear, buyers have several practical options. Buyers can request that the seller complete repairs before closing using licensed contractors.
Alternatively, buyers can ask for closing cost credits to offset future replacement costs. Our walk-through on getting a roof inspection in Palatine highlights how clear documentation strengthens negotiation leverage.
Always ensure repair agreements state that licensed professionals must complete the work. Lenders require paid invoices and final photos before clearing the file for closing.
Inspection Methods and Inspection Costs: Drone, Physical Walk, and Attic Checks
Different properties require different inspection approaches based on height, pitch, and accessibility.
| Inspection Type | Best Use Case | Key Advantages | Typical Cost Range |
|---|---|---|---|
| Ground Visual Survey | Standard single-story homes | Fast initial assessment | Low |
| Drone Aerial Imaging | Steep pitches, multi-story buildings | High-resolution slope photos without safety risks | Moderate |
| Physical Roof Walk | Walkable slopes, single-family homes | Hands-on check of shingle adhesion and flashing | Moderate |
| Full Attic & Decking Survey | Older homes, suspected leaks | Identifies timber rot, insulation flaws, and ventilation | Comprehensive |
Frequently Asked Questions About Roof Inspections for Mortgages
Can you get a mortgage on a house with an old roof?
Yes, as long as an inspector certifies at least 3 to 5 years of remaining useful life. If the roof leaks or shows active decay, the lender will require repairs before closing.
Who pays for the roof inspection during a home purchase?
The buyer typically pays for specialized inspections conducted during their contractual inspection contingency period. Sellers pay for pre-listing inspections or when clearing specific seller-cure conditions required by underwriting.
How long does a lender give you to fix roof deficiencies?
Lenders typically allow 30 days to complete mandatory repairs under standard underwriting guidelines. If bad weather delays work, an escrow holdback agreement may allow closing to proceed on schedule.
Conclusion
A damaged roof should never derail your home purchase or sale. Knowing what mortgage underwriters require ensures your property passes appraisal hurdles without expensive delays.
HomeBuild Roofing brings over 20 years of exterior experience to every Chicagoland home we inspect. Every project is owner-sold, owner-supervised, and owner-approved by Steve Mlynek. We hold a 4.9-star Google rating across 180+ reviews, won the Angi Super Service Award 2025, and earned Nextdoor Neighborhood Faves 2025.
Whether you need to clear an underwriting flag or assess remaining shingle life, we provide fast, licensed, and insured support. Contact HomeBuild Roofing today for a free roof inspection or estimate and secure your mortgage approval.